

A friend called me and said he had never been more confused by oil prices.
I knew exactly what he meant. Physical markets looked tight. Shipping through Hormuz was disrupted. Inventories were falling. The geopolitical risk was obvious. And yet oil prices were drifting lower.
My answer surprised him. I told him I thought the market had mostly gotten it right.
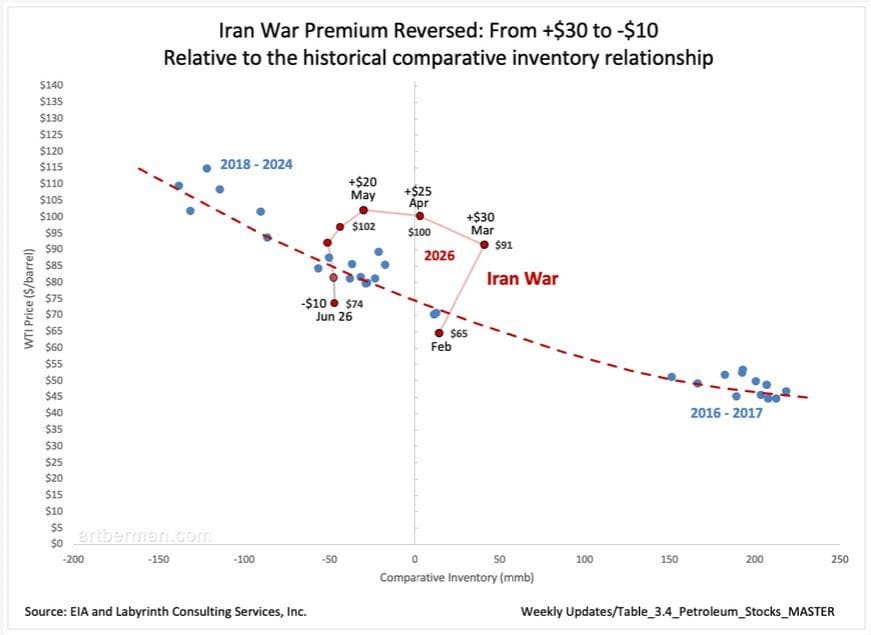
The disruption of oil flows through the Strait of Hormuz led many analysts to argue that futures prices were too low relative to the risk. Comparative inventory tells a different story. It suggests that markets had already priced a $20 to $30 war premium above the marginal price from March through May (Figure 1). Now that the conflict has begun to wind down, that premium has not merely disappeared. It has reversed. Oil is now trading about $10 below the price implied by the historical comparative-inventory relationship.
That does not mean the market is calm. It means the market has moved from pricing acute supply risk to pricing the next problem: weak demand, distorted flows, and uncertainty about what “normal” means after Hormuz.
That is a very different framing from the way most analysts see the market. Comparative inventory (CI) makes it possible.
CI compares current inventory with the market’s seasonal expectation, using the moving five-year average as a normalized benchmark. In effect, it measures whether the market is long or short relative to what it has come to regard as normal.
Markets seem to carry a kind of collective memory. They remember what level of inventory felt comfortable, what level felt dangerous, and what price was needed to push producers to drill more—or less—to balance future supply.
I have always used CI as an empirical tool. I have not worried much about why it works because it has consistently provided a reliable calibration of the marginal price implied by current inventory levels.
This time is no exception. But it also reveals something more important: people and markets value risk very differently.
People think logically, but usually from a narrow perspective. We focus on the immediate risk we can see—in this case, the loss of oil flows through Hormuz—and imagine how prices should respond.
Oil markets do something different. They take in a wider field of information: inventories, production, spare capacity, offsets to lost flows, policy responses, expectations, positioning, and history. They do not simply price what has gone wrong. They search for how the system may adapt.
In that sense, oil markets are complex adaptive systems. That does not mean markets are always right and people are wrong. It means they are doing something different. People imagine how things could break. Markets look for the price at which the system can keep functioning.
Most experienced oil observers say that predicting oil prices is a fool’s errand. I agree. But understanding the trends and forces that shape prices over time is something different.
That distinction lies near the heart of the modern dilemma. Much of quantitative science has advanced by reducing complex systems to narrow domains where prediction becomes possible. Complexity science starts from a different premise. It looks for a small set of essential processes and mechanisms that organize behavior. These models may not deliver precise forecasts, but they can reveal the underlying regularities of a system.
Comparative inventory does that for oil markets.
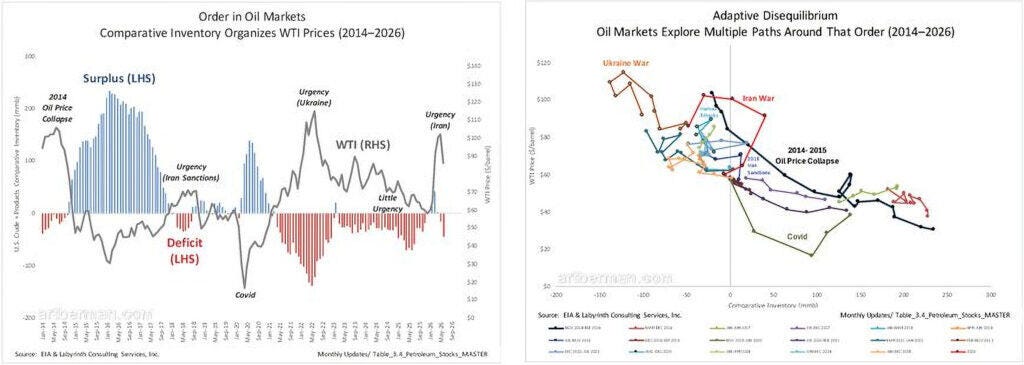
It allows us to see order in the progression of oil prices over time, as shown in Figure 2, left-hand chart. Comparative inventory organizes WTI prices around surplus, deficit, and urgency. It shows that price is not random. It is responding to the market’s changing perception of abundance or scarcity.
The right-hand chart shows the same data in state space, with the time dimension removed. At first glance, it looks disordered. But on closer inspection, each cluster of data points follows a broadly similar trajectory, even though the size of each departure varies. That reveals something different from the time-series chart. It does not show the chronological sequence of prices. It shows the paths oil markets have taken around an underlying order.
Order does not have to be simple to exist.
In the time domain, the market looks relatively well behaved. In state space, it looks adaptive. Shocks such as the 2014 price collapse, Covid, Ukraine, the 2018 Iran sanctions, and the 2026 Iran war pushed the system away from its prior path. The market then searched for a new route back toward balance.
If you are looking for equilibrium in oil markets, the right-hand chart suggests you will be disappointed. But that disappointment is itself an important insight.
Oil markets are not equilibrium systems. They operate in a constant state of adaptive disequilibrium. Prices, inventories, production, demand, policy, expectations, and risk are always adjusting to one another. The market is not trying to find a final resting point. It is continually testing paths through shocks, constraints, and changing expectations.
“Oil falls after U.S., Iran conclude talks in Doha.”
“US Oil Plunges Below $70 as Ships Keep Crossing Strait of Hormuz.”
These headlines reflect an understandable but serious flaw in how analysts often think about oil markets: the assumption that price can be reduced to a single variable.
It cannot.
Complex systems are defined by relationships among many interacting variables. Oil prices are shaped by geopolitics, inventories, spare capacity, demand, refinery behavior, policy, expectations, financial positioning, and risk. No single factor explains the outcome by itself.
A common conclusion in recent years is that geopolitical disruptions no longer matter very much. After all, oil prices during the Iran war never reached the levels seen during the Ukraine war a few years earlier.
But geopolitics was only one variable.
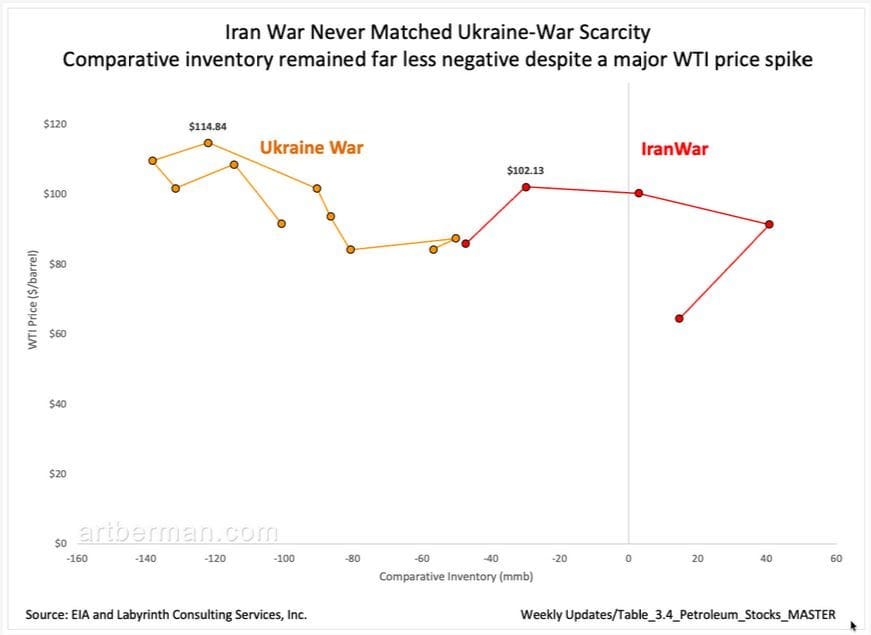
Figure 3 shows that comparative inventory during the Iran war remained far less negative than during the Ukraine war. That is a consequential difference. Think of comparative inventory like a savings account. If you have plenty of money in savings, you do not respond to an unexpected expense with the same urgency as you would if your account were nearly empty.
That is what happened during the Iran war. The geopolitical shock was real, but the market had a larger inventory cushion. Less scarcity meant less urgency. Less urgency meant lower maximum prices.
Looking only at geopolitics gives the wrong answer. The market did not ignore the Iran war. It processed the war through the inventory state it was already in.
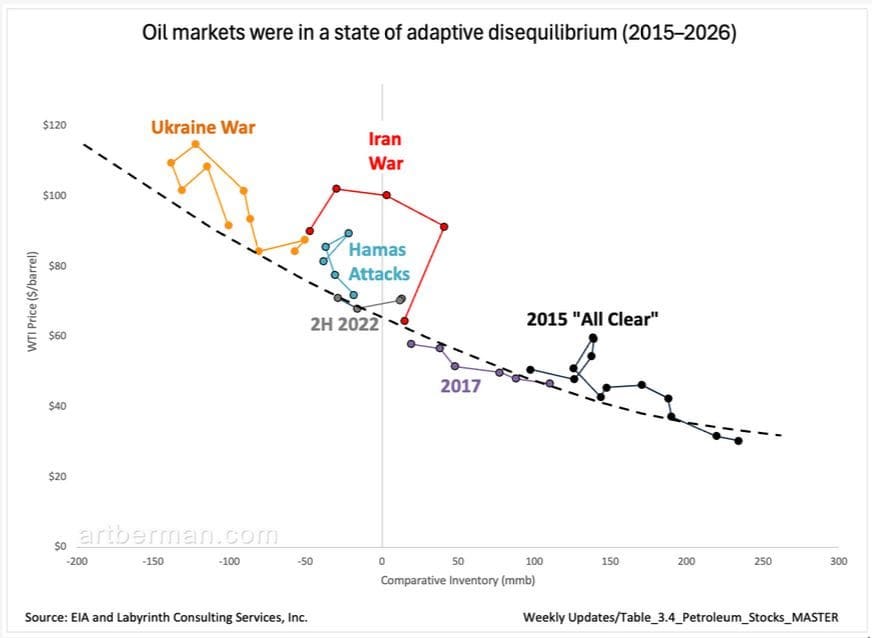
Now let’s look at the same data with additional years and events added, along with the dashed attractor line (Figure 4).
In complexity science, an attractor is a stable state, pathway, or recurring pattern toward which a system tends to evolve over time. It acts like an invisible gravitational pull, shaping long-term behavior even as shocks push the system away.
The Ukraine War, the Hamas attack on Israel in 2023, and the Iran War each introduced new forces into the oil system. They created perturbations away from the attractor.
Whenever markets face a structural change—or even the possibility of one—they shift into discovery mode. Futures markets test new price pathways as traders reassess oil flows, supply and demand, inventories, policy, logistics, and risk.
When WTI moved toward $100 during the Iran War, the market was not reacting to current inventories alone. It was exploring a possible future in which Hormuz remained constrained for months. When prices later fell back toward the comparative-inventory relationship, it was not because the past had changed. It was because the probability assigned to that future had changed.
So the market was not oscillating randomly around equilibrium.
It was continually revising its expectations about the future.
That is how adaptive disequilibrium works. Oil markets discover risk tolerance through excursions away from the attractor. Prices move higher or lower as traders test possible futures, then move back as those futures become less likely or more clearly defined. The return toward the attractor reflects a narrowing of the probability landscape as uncertainty resolves.
That also helps explain why these excursions often precede changes in the physical market rather than lag them. Futures prices are not merely describing present conditions. They are testing what the present may become.
The previous examples focused mostly on geopolitical shocks: the Ukraine War, the Hamas attack on Israel, and the Iran War. Those events pushed oil prices away from the attractor as markets explored futures defined by supply risk, war risk, sanctions, and possible disruption to physical flows.
Figure 5 shows a more nuanced case. Between 2018 and early 2021, oil markets experienced perturbations in both directions.